


What global events mean for your cash flow, and how to stay ahead.
What global events mean for your cash flow, and how to stay ahead.
When something happens on the other side of the world, it can feel far removed from day-to-day business in Geelong. However, recent global disruptions, including tensions affecting major shipping routes, are already having a real impact on Australian businesses.
For many small to medium businesses, the pressure isn’t just about rising costs, it’s about cash flow timing. And that’s where having the right financial structure in place becomes critical.
Why this matters right now
Recent global events have created a ripple effect across several key industries. While the situation may seem distant, the financial impact is being felt locally.
Some of the key pressures include:
- Fuel and transport costs
Diesel prices have increased significantly, which directly impacts trades, logistics, and service-based businesses that rely on vehicles every day. - Agriculture and primary industries
Rising fertiliser costs are putting pressure on seasonal cash flow, especially where upfront investment is required before income is realised. - Importers and wholesalers
Shipping delays and increased freight costs are pushing up the cost of goods and extending delivery timelines. - Construction and fabrication
Material costs continue to rise, tightening margins on projects that were quoted months ago.
At the same time, businesses are still operating on standard payment terms. Many are paying higher costs upfront while waiting 30 to 60 days, or longer, to receive payment. This gap is where cash flow strain begins.
The hidden challenge: timing
It’s not always the cost itself that causes stress, it’s the timing.
- Expenses are increasing immediately
- Payments from clients may be delayed
- Supply chain disruptions extend project timelines
This creates a squeeze that can impact your ability to operate smoothly, take on new work, or invest in growth.
How the right finance structure can help
This is where working with a mortgage broker or finance specialist can make a real difference. At The Hrkac Group, the focus isn’t just on loans, it’s about creating flexible solutions that support your business as conditions change.
Some of the strategies we’re helping clients with include:
- Working capital buffers
Setting up overdrafts or lines of credit to cover short-term gaps and provide peace of mind. - Invoice and trade finance
Accessing funds tied up in unpaid invoices so you don’t have to wait for payment cycles. - Refinancing existing facilities
Reviewing current loans to ensure they remain competitive and flexible as costs rise. - Leveraging equity
Using available assets to unlock cash and improve liquidity.
These aren’t one-size-fits-all solutions. The right approach depends on your industry, cash flow cycle, and long-term goals.
A local perspective
For businesses across Geelong and the surrounding region, these challenges are very real. Whether you’re in construction, agriculture, or a service-based trade, small shifts in costs and timing can have a big impact.
The key is to be proactive rather than reactive.
Having a conversation early can help you:
- Plan for potential cost increases
- Create a buffer before pressure builds
- Position your business to take advantage of opportunities
Stay one step ahead
Global events will always be outside our control. However, how you prepare and respond to them is something you can influence.
If you’re starting to feel pressure on your cash flow, or simply want to ensure your finance structure is working as hard as it should, it’s worth having a conversation.
The Hrkac Group’s Mortgage Broking team is here to help you navigate these changes with clarity and confidence.
Get in touch to discuss your options and make sure your business is set up to handle whatever comes next, contact us via email or phone (03) 5224 2366.
General Advice Warning: This information has been provided as general advice and does not take into account your individual objectives, financial situation or needs. Before acting on any information, you should consider the appropriateness of the information with regard to your personal circumstances and seek professional advice.
Buying your first home is an exciting milestone, but navigating the process, and the paperwork, can feel overwhelming. Thankfully, there’s a range of government grants and schemes available to support first home buyers in Australia. Whether you’re trying to save for a deposit or looking to reduce upfront costs, understanding your options with a Mortgage Broker is a great place to start.
Below, we break down some of the most popular grants and initiatives designed to help Australians take their first step onto the property ladder.
First Home Owner Grant (FHOG)
The First Home Owner Grant (FHOG) is one of the most well-known forms of assistance for first home buyers. Although it’s a national scheme, it’s administered at a state and territory level, meaning eligibility requirements and payment amounts can vary depending on where you live.
Key Features:
- The FHOG is typically available for those purchasing or building a new home.
- The grant amount varies by state. For example:
- In New South Wales, eligible buyers may receive $10,000 for new homes valued up to $600,000 or new home builds up to $750,000.
- In Queensland, the grant ranges from $15,000 to $30,000, depending on location.
- The grant is usually paid at the time of settlement or during the construction process.
Things to Keep in Mind:
- Existing homes typically do not qualify for the FHOG.
- There are property value caps that differ from state to state.
- This grant is often used in conjunction with other schemes.
First Home Guarantee (FHBG)
Saving for a deposit is one of the biggest hurdles for first home buyers, but the First Home Guarantee (FHBG) aims to make this process a little easier. This scheme is part of the government’s broader Home Guarantee Scheme and helps eligible buyers purchase a home with a deposit as small as 5%, without needing to pay Lenders Mortgage Insurance (LMI).
Key Features:
- The government acts as a guarantor for up to 15% of the property’s value.
- Helps buyers avoid LMI, which can be costly.
- Available to Australian citizens and permanent residents, aged 18+.
- Income thresholds apply:
- Up to $125,000 for individuals
- Up to $200,000 for joint applicants
Eligibility Notes:
- Property price caps vary based on location (capital city vs. regional).
- Applicants must intend to live in the property.
First Home Super Saver Scheme (FHSSS)
For those looking for a smarter way to save, the First Home Super Saver Scheme (FHSSS) lets first home buyers make voluntary contributions to their superannuation fund to build their deposit more efficiently.
How It Works:
- Contributions are made through salary sacrifice or after-tax payments.
- These contributions are taxed at a concessional rate, typically lower than your marginal tax rate.
- You can later withdraw these contributions, plus any associated earnings, to put toward your first home deposit.
Why Consider It?
- Potential for tax savings while you build your deposit.
- Encourages structured, disciplined savings through your super fund.
- May allow you to access your deposit sooner.
Regional First Home Buyer Guarantee
If you’re buying in a regional area, you may be eligible for the Regional First Home Buyer Guarantee, another component of the Home Guarantee Scheme.
How It Helps:
- Supports first home buyers in regional locations with similar benefits to the FHBG.
- Allows for a 5% deposit without needing to pay LMI.
- Helps address housing affordability in regional communities.
Eligibility Criteria:
- Must intend to live in the property.
- Property and income caps apply.
Additional Assistance: Stamp Duty Concessions & State-Specific Schemes
Beyond these national schemes, many state and territory governments offer additional incentives to help first home buyers, such as:
Stamp Duty Concessions:
- Some states offer full or partial exemptions on stamp duty for first home buyers.
- Eligibility usually depends on property value thresholds.
Examples of State-Based Support:
- Victoria: First home buyers may be eligible for stamp duty exemptions on homes valued up to $600,000 and concessions on homes valued up to $750,000.
- ACT & WA: Varying grants and concessions depending on location and property type.
- Queensland & NSW: Often the most generous with grants and schemes targeting new builds and regional buyers.
What Should First Home Buyers Consider?
Before applying for any grant or scheme, it’s important to understand your specific eligibility and how these programs can impact your financial situation.
Here’s what to keep in mind:
- Eligibility criteria vary widely between schemes and states.
- Check for property price caps and whether new or existing homes qualify.
- Consider how using these grants could influence your loan structure or borrowing capacity.
- Seek professional financial advice to determine which option best suits your circumstances.
Why Work with a Mortgage Broker?
Navigating the maze of first home buyer incentives can be tricky. Working with an experienced mortgage broker can help you:
- Understand your borrowing capacity.
- Identify which grants and schemes you’re eligible for.
- Compare loans across a range of lenders.
- Streamline your paperwork and application process.
- Ensure you’re maximising your entitlements while finding a loan that fits your future goals.
At The Hrkac Group, our lending experts specialise in guiding first home buyers through this process with clarity and care.
Final Thoughts
Buying your first home is one of the biggest financial decisions you’ll make, but it doesn’t have to be overwhelming. With a little knowledge and the right support, you can take advantage of the grants and schemes available and make your homeownership dream a reality.
If you’re ready to explore your options, book an appointment with our team today. We’re here to help you through every step of the journey. To make an appointment to meet with one of our friendly Geelong Mortgage Brokers, contact us via email or phone (03) 5224 2366.
General Advice Warning: This information has been provided as general advice and does not take into account your individual objectives, financial situation or needs. Before acting on any information, you should consider the appropriateness of the information with regard to your personal circumstances and seek professional advice.
Liability limited by a scheme approved under Professional Standards Legislation.
When it comes to home ownership, one of the most significant financial decisions you’ll make is choosing the right home loan. Whether you’re buying your first property, upgrading your current home, or investing in a rental, your choice between a fixed or variable home loan can greatly influence your financial journey. In this post, we’ll explore the differences between fixed and variable interest rate home loans, discuss the pros and cons of each, and provide guidance to help you decide which option best suits your needs.
Understanding Home Loans
A home loan is more than just a way to finance the purchase of a property; it’s a tool that can help you build wealth over time. At the heart of most home loans lies the interest rate—the cost you pay for borrowing money. When you take out a home loan, you generally have two interest rate options:
- Fixed Interest Rate: The interest rate is locked in for a specified period, typically between one and ten years. During this fixed term, your interest rate and your monthly repayments remain constant.
- Variable Interest Rate: The interest rate on your loan can change at any time, depending on market conditions and decisions made by the Reserve Bank of Australia (RBA). This means your repayments may fluctuate over time.
The type of interest rate you choose is a key factor in determining your overall loan costs and repayment amounts. Let’s take a closer look at each option.
Fixed Rate Home Loans
What Is a Fixed Rate Home Loan?
A fixed rate home loan allows you to lock in your interest rate for a predetermined period. This period can range from as little as one year to as long as ten years, depending on your lender and your needs. Once the fixed term begins, your interest rate remains unchanged until the period expires.
Advantages of Fixed Rate Home Loans
- Budgeting and Predictability: One of the main benefits of a fixed rate home loan is that it provides stability. You know exactly what your monthly repayments will be throughout the fixed period. This makes it easier to budget and plan your finances, as you won’t have to worry about unexpected increases in repayments due to rising interest rates.
- Protection Against Interest Rate Rises: If market conditions suggest that interest rates are likely to increase, a fixed rate loan can protect you from these hikes. You can enjoy the peace of mind knowing your rate is locked in, even if variable rates rise during your fixed term.
Disadvantages of Fixed Rate Home Loans
- Limited Flexibility: Fixed rate loans often come with fewer features than variable rate loans. For example, you might not be able to access additional funds through a redraw facility during the fixed term. If you have an unexpected expense or an opportunity to make extra repayments, a fixed rate loan might not offer the flexibility you need.
- Potential Cost of Break Fees: If you decide to pay off or refinance your home loan before the end of the fixed term, you may incur break costs. These fees can be significant and may offset the benefits of switching to a better rate or paying off the loan early.
- Missing Out on Lower Rates: While a fixed rate loan protects you from increases, it also means you won’t benefit if variable rates decrease during your fixed period. You’re committed to the locked-in rate, regardless of market improvements.
Locking in Your Fixed Rate
When applying for a fixed rate loan, you might find an attractive deal that fits your budget. However, it’s important to note that the fixed rate applied at settlement is based on the lender’s offer on that day, not at the time of your application. Some lenders offer a “lock rate” option, where you can secure the rate by paying a fee before settlement. Discuss these options with your lender to understand what works best for you.
Variable Rate Home Loans
What Is a Variable Rate Home Loan?
Variable rate home loans offer a more dynamic approach to interest rates. Instead of locking in a rate, the interest rate on a variable loan can change over time. These changes are influenced by a variety of factors, including decisions by the Reserve Bank of Australia, economic conditions, and changes in the market.
Advantages of Variable Rate Home Loans
- Flexibility: One of the biggest advantages of a variable rate home loan is its flexibility. Many variable loans come with features that allow you to make extra repayments, which can help you pay off your loan faster. Additionally, many variable loans offer offset accounts that reduce the amount of interest you pay by offsetting your loan balance against your savings.
- Potential for Lower Rates: If market conditions cause interest rates to fall, your variable rate loan will reflect these decreases, potentially lowering your monthly repayments. This can be a significant benefit if you’re comfortable with some degree of uncertainty.
Disadvantages of Variable Rate Home Loans
- Uncertainty and Fluctuating Repayments: The main drawback of a variable rate loan is that your interest rate can change at any time. This means that your repayments might increase if rates go up, which could impact your monthly budget. It’s important to assess whether you can afford higher repayments should rates rise.
- Limited Predictability: Because the rate is variable, it can be challenging to plan long-term budgets. The unpredictability of the interest rate might not be ideal if you prefer the certainty of fixed repayments.
Fixed vs Variable: Which One Is Right for You?
Deciding between a fixed and variable home loan largely depends on your personal circumstances, financial goals, and risk tolerance. Here are some questions to help you decide:
- Budget Stability: Do you prefer the predictability of knowing exactly what your repayments will be? If so, a fixed rate loan might be the better choice.
- Flexibility Needs: Do you value flexibility and the ability to make additional repayments or access extra funds through a redraw facility? A variable rate loan may suit you better.
- Risk Tolerance: Are you comfortable with the possibility of fluctuating repayments? If you’re prepared to ride out potential increases in interest rates in exchange for the possibility of lower payments when rates drop, a variable loan could be advantageous.
- Market Conditions: Consider the current economic climate. If rates are expected to rise, locking in a fixed rate can provide security. Conversely, if rates are expected to remain stable or decrease, a variable rate may offer cost savings.
It’s also worth noting that some borrowers choose to split their home loan into both fixed and variable portions. This hybrid approach allows you to enjoy the benefits of both options—locking in a portion of your loan for stability, while leaving the remainder flexible to take advantage of potential rate decreases.
Splitting Your Loan: A Balanced Approach
What Does It Mean to Split Your Loan?
Splitting your home loan means dividing your loan amount into two parts: one that operates at a fixed interest rate and another that operates at a variable rate. This approach allows you to hedge against market fluctuations by ensuring that a portion of your repayments remains consistent while potentially benefiting from any decreases in variable rates.
Benefits of a Split Loan
- Risk Management: By having part of your loan fixed, you reduce the risk of a dramatic increase in repayments if variable rates rise.
- Flexibility: The variable portion still allows you to take advantage of lower rates if they occur, providing some financial flexibility.
- Tailored Financial Strategy: Splitting your loan can be customized to match your specific financial situation. You might opt for a 50:50 split, or another ratio that reflects your comfort level with risk and your budget requirements.
Before deciding on a split, it’s crucial to discuss your options with your lender or a financial advisor. They can help you determine the ideal balance that aligns with your financial goals and risk appetite.
How to Choose the Right Option for You
Choosing between fixed and variable home loans is a highly individual decision. Here are some steps to help you make an informed choice:
- Assess Your Financial Situation: Consider your current income, future earning potential, and overall financial stability. Are you in a position to absorb potential increases in repayments, or do you need the certainty of fixed payments?
- Evaluate Your Goals: Are you planning to stay in your property for a long time, or is this a short-term investment? Your long-term goals can influence whether a fixed or variable rate is more appropriate.
- Understand the Market: Keep an eye on economic indicators, such as the Reserve Bank of Australia’s monetary policy decisions. These can provide insight into the direction of interest rates.
- Consult Experts: Home loans can be complex, and the best way to ensure you’re making the right choice is to speak with a Home Loan Specialist. The Hrkac Group’s experts are here to provide tailored advice based on your unique situation.
Choosing the right home loan is a crucial step in securing your financial future. Whether you opt for a fixed or variable interest rate home loan depends on your personal preferences, financial stability, and risk tolerance. Fixed rate loans offer the comfort of predictable repayments and budget stability, while variable rate loans provide flexibility and the potential to benefit from falling interest rates.
If you’re unsure which option is best for you, consider splitting your home loan between fixed and variable components. This balanced approach allows you to enjoy the advantages of both loan types while mitigating the risks associated with market fluctuations.
Ultimately, the decision should align with your long-term financial goals and lifestyle. It’s important to remember that both fixed and variable home loans come with their own set of benefits and drawbacks. By understanding these differences and evaluating your own needs, you can make a well-informed choice that supports your wealth creation journey.
If you have any questions or need further guidance, our Home Loan Specialists at The Hrkac Group are here to help. The expertise and experience of our Geelong Mortgage Broking team can help you with your home loan, whether it’s securing a new interest rate for you, refinancing your current loan, or discussing the finance of an investment property. Reach out today to discuss your options and take the next step toward a more secure financial future. To make an appointment to meet with one of our friendly Geelong Mortgage Brokers, contact us via email or phone (03) 5224 2366.
Liability limited by a scheme approved under Professional Standards Legislation.
A drop in your credit score can be puzzling and stressful, but understanding the reasons behind it can help you take control and improve your financial health.
Here are some common factors that might cause your credit score to decrease, along with strategies to address them.
1. Late Payments
Payment history is a significant component of your credit score. Missing payments on home loans, credit cards, utility bills, or other financial obligations can negatively impact your score. Even delayed Buy Now Pay Later (BNPL) payments can contribute to a decline.
Strategy: Set up automatic payments and alerts to remind you of due dates, ensuring you never miss a payment. This proactive approach helps you avoid late fees and potential damage to your credit score.
2. Growing Debt
Accumulating debt or having accounts sent to collections can severely damage your credit score. A payment default, defined as an amount of $150 or more overdue by 60 days or more, can be reported to credit bureaus and harm your credit rating.
Strategy: Contact your credit providers to discuss hardship options if you’re struggling. Taking proactive steps to pay off debt and demonstrating responsible financial management can gradually improve your score. Establishing a budget and prioritising debt repayment can also be beneficial.
3. Too Many Credit Applications
Applying for multiple credit accounts in a short period can raise concerns about financial stress, as it may suggest you are struggling with credit. The type of credit and provider you choose can also impact your score.
Strategy: Research and select reputable providers before applying for credit. Space out your applications to minimise the impact of hard inquiries on your credit score. Each application can slightly lower your score, so be strategic about when and where you apply.
4. Lack of Stability
Frequent changes in your residential or employment status may indicate higher credit risk and impact your credit score. Stability is often seen as a sign of financial responsibility.
Strategy: Maintain stability in your employment and residence to positively impact your credit score over time. Keeping a consistent job and address can signal to lenders that you are a lower-risk borrower.
5. Business-Related Issues
If you are a business director or proprietor, your financial decisions and responsibilities can influence your personal creditworthiness. For example, a history of closing and opening new businesses to avoid debt payments can affect your credit report.
Strategy: Be mindful that your financial behaviour both as a consumer and a business proprietor can impact your credit score. Maintaining a good credit record and managing business finances responsibly are crucial for both personal and business credit health.
6. Inaccuracies
Errors in your credit report, caused by mistakes from credit providers, can affect your score. Common errors might include incorrect information about your payment history or account status.
Strategy: Review your credit report regularly and contact your credit provider to correct any mistakes. You can also use Equifax’s Corrections Portal to request an investigation and amend inaccuracies. Regular checks can help you catch and resolve errors early, preventing potential damage to your credit score.
7. Identity Theft
If you fall victim to identity theft, fraudsters may open new credit accounts in your name. Accumulated debt and missed payments on these accounts can significantly damage your credit score.
Strategy: If you suspect identity theft, consider placing a ban on your credit report while you work to resolve the issue. Staying vigilant and addressing any signs of fraud early can help minimise damage. Additionally, monitoring your credit report regularly can help detect suspicious activity before it significantly impacts your score.
Stay Informed and Take Action
Regularly monitoring your credit score and report is crucial to understanding and addressing changes. Services like GetCreditScore allow you to check your credit report overview, including your score, for free online. By keeping an eye on your credit profile, you can identify and resolve issues that might be affecting your score.
Understanding these factors and taking proactive steps can help you maintain a healthy credit score and improve your financial well-being. Staying informed about your credit profile and addressing issues as they arise is essential for long-term financial health.
Conclusion
Understanding the reasons behind a drop in your credit score is crucial for maintaining your financial health. Factors such as late payments, growing debt, excessive credit applications, and inaccuracies can all influence your credit rating. Additionally, issues related to identity theft and business-related financial behaviour can also impact your score. Regular monitoring of your credit report and addressing any issues promptly are key steps in managing and improving your credit score effectively.
At The Hrkac Group, we are dedicated to supporting you in navigating your financial concerns and achieving your goals. Whether you need assistance with credit management or other financial matters, our experienced team of Geelong Mortgage Brokers is ready to help. By partnering with us, you can gain valuable insights and practical strategies to improve your financial health. Contact us today via our online booking form or call our Geelong office on (03) 5221 2355 to schedule a consultation and take the next step towards a healthier financial future.
Choosing the best Mortgage Broker Geelong
Buying a home and taking out a home loan of any size is a big commitment. Whether it be your first house or your third, the process can be both daunting and overwhelming. Having an expert mortgage broker on your side to help guide you through the process can make a world of difference to your home buying and lending experience.
With endless options at your fingertips when it comes to Mortgage Brokers, it’s essential to find one who can work with you, and your family’s needs effectively and help you secure a suitable home loan.
To choose the best mortgage broker in Geelong for you, a little bit of research will go a long way to help with your decision. To help streamline the process for you, there are several things that you should take into consideration to help with your decision.
What exactly can a Mortgage Broker do for me?
Mortgage brokers essentially work as the link between you, and various lenders, both with banks and non-bank institutions.
We always have your best interest at the forefront of our minds. We work to align your individual requirements with the loan’s attributes to ensure you get the most out of your home or business loan, ensuring the most favourable rate is secured for you on every occasion.
Having an experienced mortgage broker on your side, takes the stress off your shoulders, as it is our job to research and compare the market to suit your needs, communicate with your chosen lender (so you don’t have to) and help guide you through the entire process. Answering any questions you have throughout the process, as well as assisting with finalising paperwork.
Researching for the best Mortgage Broker
Doing thorough research may seem overwhelming, but trust us, starting your journey with proper research will simplify the rest of the process. This groundwork will equip you with the knowledge and expertise similar to that of a Mortgage Broker, who will take care of the rest for you!
How extensive is their experience?
Experience matters. If it didn’t, you would most likely just roll with the first Mortgage Broker that appeared on the top of your Google search and your experience may be underwhelming.
Look into how many years of experience they have. The more years of experience they have under their belt, the more confidence you will have knowing you are in the right hands when you find a mortgage broker best suited for you.
Whether you are looking into the services of a company, or an individual, some of the most important questions to find the extent of their experience are:
What qualifications and accreditations do they have?
Qualified mortgage brokers should have the following:
- Certificate IV in Finance and Mortgage Broking
- Be accredited under the National Consumer Protection Act
- Be a member of the Mortgage & Finance Association of Australia (MFAA) and/or the Finance Brokers Association of Australia (FBAA)
Are they licensed?
All mortgage brokers should have their own Australian Credit Licence or alternatively, as required by the Australian Securities and Investments Commission (ASIC), they should be qualified to act as an authorised Credit Representative.
How many lenders have they worked with?
Brokers are limited to a list of banks they can obtain loans from, which is referred to as their “lender panel.”
Ensuring your broker has worked with multiple lenders is crucial for your financial interests as it provides you with a wider range of loan options.
A reliable broker should have a diverse range of lenders on their panel, as it will help to utilise different options based on the borrowers’ situation. It is best to confirm the number of lenders the broker has on their panel, how many they work with, and inquire about the reasons behind their choices.
Do they have positive reviews?
Customer testimonials provide the most authentic insight into a product or service. Explore their Google reviews to read about others’ experiences. What do customers say about the services reliability, friendliness, and honesty? How prompt was their response?
Ideally, a reputable mortgage broker will have a portfolio of satisfied customers to share with the community and potential new clients.
If any of your family or friends have engaged with the services of a mortgage broker recently, ask them about their experience. Were they satisfied with their broker, and the guidance received? What qualities would they seek in their future broker?
What are the fees, charges & commissions?
By law, mortgage brokers must explain exactly how they are compensated, or paid. Typically, brokers earn a commission based on a percentage from the bank that is granting the loan, which is why there is no costs associated for you to use the services of a mortgage broker.
Consider it a warning sign if a broker struggles to address fundamental inquiries regarding charges, commissions, and ownership structures. Any reliable mortgage broker should consistently provide clear and transparent information about their business operations and services.
Find the best Mortgage Broker Geelong at The Hrkac Group
If you are looking for the best Mortgage Broker Geelong, our team at the Hrkac Group is here to provide you with practical and effective financial advice.
We’ll assist you in finding the best home, or business loan solution tailored to your specific needs. Our honest, knowledgeable team of Geelong mortgage brokers will give you the confidence to negotiate for your future, so together, we can develop and maintain your wealth with our transparent approach.
Contact our team of Mortgage Brokers today on (03) 5224 2366 or book an appointment here.
If you have had your current home loan for a number of years, it is likely your needs have since changed. That, or you may be missing out on flexible features or add-ons that have since become available.
Refinancing your home involves paying out your current loan with a new one. In many cases, this will be with a different bank entirely. Why? This may allow you to select certain features that better suit your lifestyle, wants and needs.
Here are 8 reasons why you could consider refinancing your home:
1. Save on Fees
Your interest rate will have a significant impact on how much you actually pay on your mortgage. If you have had your loan for a number of years, you may be paying loyalty tax. This is when lenders charge long-term customers a higher interest rate, compared to new customers. Securing an interest rate just 0.5% lower than your existing loan can see you save thousands. Ultimately resulting in your loan being paid off quicker, and who doesn’t want those extra dollars in their pocket?
It is important to remember your home loan is more than the interest rate. All lenders measure their rates differently, which is why it is so important to speak with a Lending Specialist or Mortgage Broker to ensure you are reviewing all aspects of the loan before making the change.
2. Customise your loan
It is likely that your personal circumstances will change over the course of your home loan and you may need to alter your loan accordingly. When getting your home loan years ago, it may have included features that no longer suit you today, or you have found that over time, the features on your current loan are just not being maximised. Adding or removing features to better suit your lifestyle can help give you the flexibility you need. There are a range of features available to you, including flexible repayments, redraw facilities or even offset accounts. As always, it is best to consult our team of Geelong Mortgage Brokers to explore the best path for you.
3. Opt for a fixed rate
Fixed rates work really well in the right situations however upon the end of your fixed rate term, you will be transferred to a higher variable rate by default. However, refinancing your fixed loan once it has ended, may help you avoid having to pay any associated fees with leaving a fixed home loan early.
4. Access home equity
If you want to access your home equity, refinancing is the way to do it. Your equity is the portion of your home that you own outright. You can calculate your equity by subtracting your remaining home loan from the balance of your home’s current value. Accessing your equity can then help fund major purchases or investments.
5. Investment Opportunities
Refinancing your home can help you maximise your equity on your home. You could then use those funds to invest in real estate, shares, or other opportunities.
7. Facilitate Renovations
Enhance your property’s value and move closer to achieving your dream home by undergoing renovations on your property. To avoid having to take out a new loan to fund your renovations and ensure your savings stay in your bank, think about using the equity in your home which can be unlocked by refinancing your home.
7. Debt Consolidation
You may have other debts, including personal loans, car loans or credit cards.
Debt consolidation involves combining those other debts with your home loan. This simplifies repayments and makes managing your repayments more convenient.
8. Switching Lenders
You may not be 100% satisfied with your current lender. This could be due to a number of factors, some of them being: inadequate website, mobile app or in-person services, inflexible repayment methods or a negative experience with the customer service provided. Whatever the reason, if you do decide to refinance based on the lender, ensure you are taking into consideration all aspects of the new loan and not just the lender.
Geelong Mortgage Brokers at The Hrkac Group
If you are considering refinancing your home loan, there are steps you need to take to ensure you are eligible to do so. Our team of Geelong Mortgage Brokers are dedicated to helping you ensure your home loan journey is as simple and stress-free as possible. We have access to a range of home loans offered by banks and non-banking lenders, to ensure we find the best suitable option for you.
Take control of your financial future by meeting with our team of Geelong Mortgage Brokers and home loan specialists at The Hrkac Group. Make an appointment today via our Contact Us page, or phone us on (03) 5224 2366.
General Advice Warning
This information has been provided as general advice. We have not considered your financial circumstances, needs, or objectives. You should consider the appropriateness of the advice. You should obtain and consider the relevant Product Disclosure Statement (PDS) and seek the assistance of an authorised financial adviser before making any decision regarding any products or strategies mentioned in this communication. Whilst all care has been taken in the preparation of this material, it is based on our understanding of current regulatory requirements and laws at the publication date. As these laws are subject to change you should talk to an authorised adviser for the most up-to-date information. No warranty is given in respect of the information provided and accordingly, neither nor its related entities, employees, or representatives accepts responsibility for any loss suffered by any person arising from reliance on this information.
The dream of owning a home is deeply ingrained in Australian culture. For many, it represents a significant milestone in their lives, symbolising financial security and stability. But, the rising cost of housing in many parts of Australia has made this aspiration increasingly challenging for first-time buyers.
Furthermore, the dream of owning a home has been made even more difficult due to stricter lending practices by banks, sluggish wage growth relative to inflation, and concerns about fluctuating interest rates. In response to this challenge, commencing on July 1st, 2023, the government’s Home Guarantee Scheme expanded its eligibility criteria. It has been made to be more accessible for individuals who have long aspired to homeownership.
Understanding the First Home Guarantee Scheme
The First Home Guarantee is an Australian Government initiative. It’s aimed at speeding up the ability to buy a home for eligible buyers. The Scheme comprises several key components, each aimed at assisting first-time buyers in different ways:
-
First Home Guarantee
This component of the Scheme helps eligible first-home buyers secure a home loan with a lower deposit. Typically, banks require a deposit of at least 20% of the property’s value. Under the scheme, eligible buyers can purchase a home with as little as a 5% deposit. The government guarantees the remaining portion of the deposit, effectively eliminating the need for costly Lenders Mortgage Insurance (LMI). This makes homeownership more attainable for those who may have been struggling to save a large deposit.
Beginning on July 1, the upcoming changes will extend eligibility beyond singles and de-facto couples. Now encompasses family members, siblings, and friends who can collaboratively apply and divide the expenses associated with a first home deposit.
-
Regional First Home Buyer Guarantee
This program is for eligible first-home buyers looking to purchase their first home in a regional area. It enables them to do so with a deposit as low as 5%, without incurring the expenses associated with LMI.
On July 1, the upcoming changes will extend eligibility beyond singles and de-facto couples to encompass family members, siblings, and friends who can collaboratively apply and divide the expenses associated with a first home deposit.
-
Family Home Guarantee
This initiative offers eligible single parents with dependents the opportunity to apply for a mortgage with as little as a 2% deposit, without attracting LMI, thanks to the government acting as guarantor. It’s accessible to both first-time homebuyers and single parents seeking to enter or re-enter the property market, whether they intend to purchase an existing property or build a new home. This scheme is intended to help alleviate some of the financial stress that often accompanies single parenthood.
Starting from July 1, the forthcoming changes will broaden eligibility criteria to encompass not only single parents but also single legal guardians of children, including siblings, aunts, uncles, and grandparents.
Who’s Eligible to Apply?
To apply for the Scheme, following the changes that took effect on July 1, prospective homebuyers must meet the following criteria:
- Citizenship or Residency: Applicants must be Australian citizens or permanent residents at the time they enter into the loan. Commencing July 1, permanent residents will now be eligible for all three guarantees offered under the scheme.
- Age Requirement: Homebuyers must be at least 18 years of age to be eligible.
- Income Limits: The income threshold for eligibility is an annual income of up to $125,000 for individuals or $200,000 for couples, as indicated on their Notice of Assessment issued by the Australian Taxation Office.
- Deposit: A minimum deposit of 5% of the property’s value is required. However, for those applying for the Family Home Guarantee, a minimum deposit of 2% is sufficient.
- Owner-Occupancy: Applicants must intend to use the purchased property as their primary residence, establishing them as owner-occupiers.
- First Homebuyer Status: Eligibility extends to first-time homebuyers who have not previously owned or held an interest in a property in Australia. Additionally, homebuyers who have not owned a property in the past 10 years are eligible under the scheme.
- Loan Approval: Applicants should be capable of securing a loan through a participating lender.
What Type of Property can be Bought?
In order for a property to qualify for eligibility, it must meet the criteria of being categorised as a ‘residential property’. Residential properties that meet the eligibility criteria encompass the following:
- An existing house, townhouse, or apartment
- A house and land package
- Land and a separate contract to build a home
- An off-the-plan apartment or townhouse
The program aids in acquiring or constructing a modest home, with the condition that the residential property’s value does not surpass the applicable price cap for its location. The specific price caps for capital cities, major regional centres, and regional areas can be referenced here.
Key Considerations when Financing Your New Home
When it comes to financing your new home, it’s essential to temper your excitement with thoughtful consideration and careful decision-making. Owning a home is a significant step. It demands thorough research and prudent choices that can profoundly impact your future as a homeowner. Several key considerations should include:
-
Type of Home
Begin by defining the type of home you’re seeking. Are you in pursuit of your dream home, or is an entry-level home more aligned with your current goals? Consider your family’s needs, the required space, and whether the home should accommodate future growth. Additionally, assess if the neighbourhood matches your lifestyle preferences and necessities.
-
Financial Assessment
Evaluate your financial situation. Determine the amount you can save for a deposit, as a larger deposit can reduce long-term interest costs on your loan. Ensure your income and financial stability align with your new home purchase and think about whether you’ll be able to consistently service your mortgage. Explore potential government initiatives or subsidies for which you may be eligible.
-
Home Loan Considerations
Delve into the specifics of your home loan. Have you consulted with a mortgage broker to explore various loan options? Understand whether you’ll be subject to paying LMI and assess whether a fixed or variable interest rate is more suitable for your circumstances. Additionally, consider whether you’ll secure your home loan through a traditional bank or an alternative lender.
Mortgage Brokers Geelong
By taking these factors into account and speaking with our expert mortgage brokers in Geelong, we can help you confidently finance your new home and set a solid foundation for your homeownership journey.
The expert lenders at The Hrkac Group are committed to helping borrowers get the most from their lending. Our team of financial experts can help you create a financial plan that works for you and your individual circumstances and can help you make the right decision about managing your home loan. If you want to discuss your options, speak to an expert Geelong Mortgage Broker at The Hrkac Group.
Our Geelong Mortgage Brokers’ expertise and experience in facilitating your home loan can help ensure a positive experience for you. To make an appointment to meet one of our friendly Geelong Mortgage Brokers, feel free to contact us via email or phone (03) 5221 2355.
The information provided in this blog is of a general nature only and is not intended as either advice or recommendations and is not tailored to your specific circumstances. Please also note that this does include any information on any Payroll requirements imposed by any State or Territory Governments outside of the State of Victoria. Please contact our partner – SIBS Bookkeeping team or us – the Hrkac Group Accountants team – if you would assistance as to how, or if, any of the abovementioned would apply to you.
Liability limited by a scheme approved under Professional Standards Legislation.
In the realm of personal finance, the term “credit score” often comes up, though many are unsure of its significance. Credit scores often serve as a crucial component in the decision-making process of potential lenders and creditors. While credit scores are not the sole determinants of your financial fate, they provide a general assessment of your suitability for a loan.
In this comprehensive guide, we explore the ranges of credit scores, shed light on a lender’s perspective, examine the factors that impact credit scores, and offer actionable strategies to cultivate responsible credit behaviour. By understanding the nuances of credit scores and proactively managing your financial health, you can unlock opportunities for better loan terms and financial well-being.
What is a credit score?
A credit score is a three-digit number ranging from 300 to 850. Credit scores are calculated using information in your credit report, including your payment history, the amount of debt you have, and the length of your credit history.
There are many different scoring models, and some use additional data in their calculations. Credit scores are used by potential lenders and creditors, such as banks, credit card companies, or car dealerships, as one factor when deciding whether to offer you credit, like a loan or credit card. It helps them determine how likely you are to pay back the money they lend.
So what is a good credit score?
When it comes to credit scores, it’s important to understand that everyone’s financial and credit situation is unique, and there is no “magic number” that guarantees better loan rates and terms. However, credit scores can provide a general assessment of your creditworthiness.
Here are the typical credit score ranges:
- Fair Credit: Scores ranging from 580 to 669 are considered fair.
- Good Credit: Scores between 670 and 739 fall into the good credit range.
- Very Good Credit: Scores from 740 to 799 are categorized as very good credit.
- Excellent Credit: Scores of 800 and above are considered excellent.
Lenders tend to categorise borrowers based on their credit scores to assess risk and determine loan terms.
Here’s how lenders generally view borrowers based on credit scores:
- Acceptable or Lower-Risk Borrowers: Individuals with credit scores of 670 and above are seen as acceptable or lower-risk borrowers. They are more likely to qualify for favourable loan terms and credit opportunities.
- Subprime Borrowers: Those with credit scores ranging from 580 to 669 fall into the category of subprime borrowers. They may face challenges in qualifying for better loan terms due to their credit score, as lenders consider them to be at a higher risk compared to those with higher scores.
- Poor Credit Range: Borrowers with credit scores below 580 generally fall into the poor credit range. They may encounter difficulties in obtaining credit or qualifying for better loan terms, as lenders perceive them to be high-risk borrowers.
Different lenders have different criteria when it comes to granting credit, which may include information such as your income or other factors. That means the credit scores they accept may vary depending on that criteria.
Credit scores may differ between the three major credit bureaus (Equifax, Experian, and TransUnion) as not all creditors and lenders report to all three. Many creditors do report to all three, but you may have an account with a creditor that only reports to one, two, or none at all. In addition, there are many different scoring models available, and those scoring models may differ depending on the type of loan and lenders’ preference for certain criteria.
What Factors Impact Your Credit Score?
Here are some tried and true behaviours to keep top of mind as you begin to establish – or maintain – responsible credit behaviours:
- Pay your bills on time, every time. This doesn’t just include credit cards – late or missed payments on other accounts, such as cell phones, may be reported to the credit bureaus, which may impact your credit scores. If you’re having trouble paying a bill, contact the lender immediately. Don’t skip payments, even if you’re disputing a bill.
- Pay off your debts as quickly as you can. By reducing your overall debt load, you can improve your credit utilisation ratio, which is the amount of credit you’re using compared to your total available credit. A lower credit utilisation ratio can positively impact your credit score.
- Keep your credit card balance well below the limit. A higher balance compared to your credit limit may impact your credit score. Aim to keep your credit utilisation ratio below 30% to maintain a good credit score.
- Apply for credit sparingly. Applying for multiple credit accounts within a short time period may impact your credit score. Each application typically results in a hard inquiry on your credit report, which can temporarily lower your credit score. Only apply for credit when you truly need it and can responsibly manage additional credit accounts.
- Check your credit reports regularly. Request a free copy of your credit report and check it to make sure your personal information is correct and there is no inaccurate or incomplete account information. You’re entitled to a free copy of your credit reports every 12 months from each of the three nationwide credit bureaus by visiting www.annualcreditreport.com. By requesting a copy from one every four months, you can keep an eye on your reports year-round. Remember: checking your own credit report or credit score won’t affect your credit scores.
- Dispute inaccuracies. If you find information you believe is inaccurate or incomplete, contact the lender or creditor. You can also file a dispute with the credit bureau that furnished the report. At Equifax, you can create a myEquifax account to file a dispute. Visit our dispute page to learn other ways you can submit a dispute.
A good credit score is crucial for accessing favourable credit terms and opportunities. It represents your creditworthiness and the likelihood of paying back borrowed money. By understanding how credit scores are calculated and practicing responsible credit behaviours, you can work towards achieving and maintaining a good credit score, which opens up doors to better financial opportunities. Remember, building good credit takes time and discipline, but the effort is well worth it in the long run.
Mortgage Broker Geelong
As you prepare to take the leap into home ownership, it’s important to consult with a Mortgage Broker to understand your obligations.
The expertise and experience of our Geelong Mortgage Broker team at The Hrkac Group can help you with securing a home loan. If you need assistance or advice, please get in touch. To make an appointment to meet with one of our friendly Geelong Mortgage Brokers, contact us via email, or phone (03) 5224 2366.
Liability limited by a scheme approved under Professional Standards Legislation.
The Reserve Bank of Australia has said it expects about half of all outstanding fixed home loans to switch to variable rates in 2023. This equates to around 800,000 home loans, totalling about $350 billion.
Many Australians were lucky to lock in record-low fixed interest rates on their mortgages in the last few years; but for some, this may be coming to an end in 2023. This will leave affected households paying two to three times their current fixed rate, due to rapidly rising interest rates.
If your fixed-rate home loan is approaching its end, you’ll need to make some decisions. Should you re-fix your loan at a new rate, change to a variable rate, or even consider refinancing to a new mortgage provider?
In this article, we’ll talk through your options when it comes to preparing for the end of your fixed interest rate.
What is a fixed-rate mortgage?
A fixed-interest rate home loan is one where the rate of interest you pay on your mortgage is locked in for a certain period. In Australia, a fixed rate typically lasts between one and five years. During the time your rate is fixed, your interest rate and your compulsory repayments won’t change.
If you fix your interest rate when interest rates are low, you could be saving yourself from paying more when interest rates rise. But for this reason, fixed interest rates tend to be a bit higher than variable rates. While it makes it easier to budget for the future as you know exactly what your repayments will be, you could also be missing out on big savings when the interest rate falls.
Also, many fixed-rate mortgages do not have offset accounts, which means that extra savings cannot be used to reduce interest paid on the loan. With a fixed rate, you are sometimes impeded in terms of how quickly you can pay off the loan. A break fee may be incurred if you want to pay it off early.
What is a variable rate mortgage?
A variable-rate home loan features an interest rate that may change over time, according to the rise and fall of interest rates. If you choose a variable rate home loan, you may be able to take advantage of any interest rate decreases over your loan’s term, meaning you pay less interest on the home loan balance and your repayments go down.
On the other hand, when the interest rate increases, so too will the amount of interest you’re paying, meaning your repayments will go up.
How can I prepare for the switch?
If you don’t do anything before your fixed term rate lapses, your mortgage provider generally switches your loan to its standard variable rate, which can be much higher than some of the discounted options available to new customers.
If you are worried about what will happen when your fixed-rate mortgage ends, you should speak to a trusted financial expert at your earliest convenience. This helps you avoid any scenario where you are stuck with the imposed rate your current lender offers when the fixed rate period ends.
It’s important to research your options because, with each rate increase, your borrowing capacity can be reduced because lender calculations on household expenditure and expenses change. And as house prices fall, you could end up owing more on your house than what it is currently worth. Here are the steps we recommend you take prior to the end of your fixed interest rate.
- Negotiate with your current lender
Speak to your current lender in advance to find out what your rate will change to. This gives you an opportunity to compare with other rates available in the market and think about whether switching providers is right for you. You could also negotiate a better rate to save you the effort of moving to a new provider. - Research what other lenders can offer
See how your loan stacks up against other home loans out there to determine if you’re getting a competitive interest rate. If you do find a better offer, switching providers can be the right move. But make sure you’re aware of the costs involved in switching, as borrowing costs and fees can sometimes be greater than the amount you would save. - Consider re-fixing your home loan
Even though now may not be the best time to go with this option, if you have enjoyed the certainty that comes with a fixed-rate loan, you can refix your mortgage with an up-to-date interest rate. However, you will be locked into the new fixed interest rate for a period of your loan term, unless you choose to end the contract earlier which may result in break fees. Be sure to also carefully check out the features of a fixed loan too, such as fee-free extra repayments, redraw, and linked offset accounts. Many fixed-rate loans do not provide these features. - Consider splitting your loan
If you can’t decide on a variable or fixed rate, or if you want a combination of flexibility and predictability, you can potentially have part of your mortgage fixed and part variable. For example, you could have 60% of your loan on a fixed rate and 40% on a variable rate. This approach can offer you the best of both worlds. The variable rate component lets you take advantage of any interest rate falls, while the fixed portion shelters part of your loan from rising interest rates. - Talk to a trusted lending professional
If you can’t decide which option is best for you, a mortgage expert may be able to offer you advice. They can look at your finances and recommend options that suit your specific needs. They’ll also be able to guide you through the process of switching to another provider if that’s what you decide.
If you are worried about what will happen when your fixed-rate mortgage ends, you should speak to a trusted financial expert at your earliest convenience. Before you make any decisions, crunch the numbers with an online mortgage switching calculator.
The expertise and experience of our Geelong Mortgage Broking team at The Hrkac Group can help you with your home loan, whether it’s securing a new interest rate for you, refinancing your current loan, or discussing the finance of an investment property. To make an appointment to meet with one of our friendly Geelong Mortgage Brokers, contact us via email or phone (03) 5224 2366.
Liability limited by a scheme approved under Professional Standards Legislation.
With the state of the world’s economies, persistently high and rising inflation, and so much uncertainty, homeowners are bracing themselves for even more rate hikes from the Reserve Bank of Australia (RBA). This is impacting Australians in all aspects of their spending, and even though housing prices are reported to be declining, homeowners are still being forced to borrow more and more to enter the market.
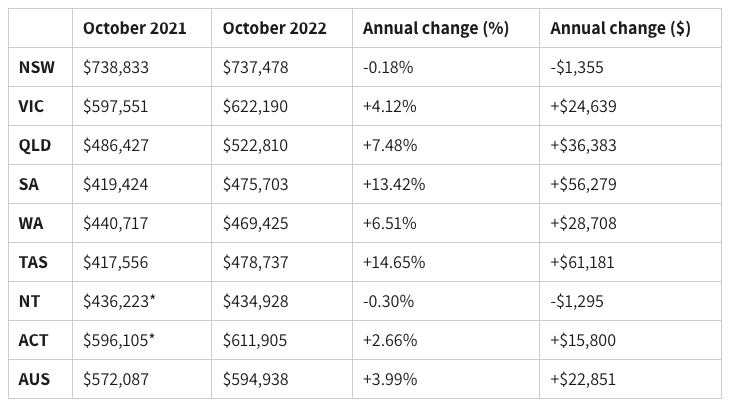
The latest lending indicators from the Australian Bureau of Statistics (ABS), in the table below, show that the average mortgage size (for owner-occupier dwellings) was $594,938 in October 2022 — up from $572,087 in October 2021.
Although the average Australian home loan has only increased by $22,851 this is after the impact of surging property prices that was witnessed across the country over the pandemic. According to property research firm CoreLogic, Australian housing values increased 28.6% over the latest upswing, which equates to an average increase of $170,700.
Lenders are feeling the burden of increasing interest rates, rising inflation, and increases in loan repayments.
Average loan size by state and territory — October 2021-22 (Source: ABS)
Where is the market headed?
The current trend of the Australian property market is being driven by how the rate hikes have affected affordability. There has been a decrease in demand for purchasing homes and an increase in home listings. With a shift in demand towards cheaper and more affordable homes like units. This is likely to continue driving growth in the unit sector while the housing market is levelling off.
As a first home buyer, most of the average loan values listed above are still below the state and territory property price caps for the First Home Loan Deposit Scheme and New Home Guarantee initiatives. These schemes allow eligible first home buyers to purchase a home with as little as 5% deposit without paying Lenders Mortgage Insurance, which on average helps people purchase their first home 4 years sooner. So taking advantage of these schemes is a great tool helping you get into the market sooner before prices and the amount you need to borrow rises.
No one gets ahead by waiting
Amid the confusion of interest rates, inflation, property prices stabilising, many are wondering if now is the time to buy. If you got one lesson out of the pandemic, it should have been buy and buy now. During the early stages of the pandemic, many people held back from buying with so much uncertainty and fears of a property price crash. However, the opposite occurred and prices soared, leaving those who were just watching in the dust. Instead of trying to time the market perfectly, you should aim to buy as soon as you have a deposit and your finances in order. The sooner you get into the market, the more time you will have to benefit from your property’s growth.
The expertise and experience of our Geelong Mortgage Broking team at The Hrkac Group can help you in the process of obtaining a home loan, refinancing your current loan, or to discuss the finance of an investment property, whatever your personal circumstances. To make an appointment to meet with one of our friendly Mortgage Brokers today, feel free to contact us via email or phone (03) 5224 2366.
The information provided in this blog is of a general nature only and is not intended as either advice or recommendations and is not tailored to your specific circumstances. Please also note that this does include any information on any Payroll requirements imposed by any State or Territory Governments outside of the State of Victoria. Please contact our partner – SIBS Bookkeeping team or us – the Hrkac Group Accountants team – if you would assistance as to how, or if, any of the abovementioned would apply to you.
Liability limited by a scheme approved under Professional Standards Legislation.
If you have a home loan, or are in the market to buy a house, you are most certainly aware by now that interest rates are rising at a rapid rate. The Reserve Bank has this month raised the cash rate by 0.5 of a percentage point for the fourth straight month in a row, and governor Philip Lowe has said the board expects to increase interest rates even further over the months ahead. The cash rate target of 2.35 per cent is the highest since the beginning of 2015. As a result, home loan rates are also certain to rise.
Governor Lowe’s post-meeting statement once again reiterated that the bank’s board is “committed to doing what is necessary” to bring inflation back within the bank’s 2-3 per cent target range “over time”. Analysis by RateCity suggests that this most recent increase will add an extra $200+ per month to repayments on a $750,000 mortgage. The total increase in monthly repayments on a $750,000 mortgage since the RBA began lifting the cash rate from its all-time low of 0.1 per cent in May, will be over $900.
These rises aren’t unprecedented; in 1994, the cash rate went from 4.75 per cent to 7.5 per cent in just five months. All the same, things may be feeling a bit scary in your household right now. So what should you do in response? Here are five suggestions:
1. Don’t panic
Don’t panic, there are many ways to survive and thrive in these challenging times. Your lender wouldn’t have approved your mortgage unless they were sure that you could cope with a worst-case-scenario series of rate rises. So unless your financial position has severely deteriorated since then, you should be able to cope with higher repayments. While a higher mortgage repayment may strain your budget and certainly cause concern, it’s most likely never going to get to the point where you must default on your mortgage. Soaring rates, increasing inflation, and oil price hikes are all part of the economy. There are things you can do to prepare for rate rises and keep your finances on track.
It may help to understand exactly how the rate increases will impact your bottom line. If you have a financial planner, mortgage broker or someone who can assist you in these matters, book in a catch up. By understanding how much more money you need to find each month, you can start to make the proper arrangements. Stay positive and don’t despair. Rising interest rates can be challenging. Talk to one of our expert lenders if you need help understanding your options.
2. Get ahead of any problems
If you think you might struggle to continue making your repayments, contact your lender now to discuss your options. It’s important you make contact before you miss a repayment, not after, because the more warning you give your lender, the more flexible they’re likely to be. No one wants you to default on your loan. Understand your options. If you’re struggling to make ends meet, there are other avenues you can take.
When speaking to your lender about your circumstances, see if they have available options to defer, pause or reduce your repayments if you are suffering from financial hardship. Many lenders in Australia offer a hardship policy, and you should speak to them if you feel the situation is becoming too difficult for you to manage.
3. Budget for rate rises
Make a budget and commit to it. This will help you stay across your finances and ensure you’re not overspending. Understanding where your money goes is important for anyone, under pressure from rate rises or not. If you don’t already have one, create a budget that encompasses all of your income and all of your expenses. Make sure that you capture everything, including major expenses (such as loan repayments, bills, groceries, and fuel) and also smaller expenses and luxuries, (like take-away, streaming services, etc.). Once you have an idea of your actual cash flow, you can start to make more informed decisions about your spending.
If rates increase, you must find the increased repayment in the budget somewhere. Assume your mortgage rate will rise by 2 percentage points. Calculate what your new monthly repayment would be and start paying it now. You can put the extra money into an offset account, a redraw facility or a special savings account. If you have a variable home loan, an offset account can be a useful tool. You can still use it as a regular transaction account but, just by having the money sitting there, it reduces how much interest you’re paying on your loan.
4. Improve your savings rate
Finding crafty ways to reduce your expenses could give you a bit more breathing room as rates rise. When times become a little tougher, it’s always good to look at where your money is going and try to reduce your habit-spending where possible. We tend to overlook smaller purchases, like your daily take-away coffee, that bottle of wine with dinner, or other minor impulse purchases. Perhaps you could skip dining out every couple of weeks, cancel your weekly meal box or reassess some of the household brands you buy. Reducing your overall spending is the main objective if you find yourself needing to free up some extra cash to make way for increased repayments.
Now could also be a great time to ask for a raise or a promotion. Employees are in a unique position to ask for a raise this year, because high inflation and tight labour markets are expected to continue. Additionally, you could look for new income opportunities on the side.
5. Switch to a better loan
The home loan market is intensely competitive, which is why lenders often charge new borrowers lower interest rates than loyal customers. So you could be making big savings by refinancing to a lender offering a comparable loan at a lower rate. Try finding one with an offset account attached to the loan account. This is an effective tool to bring down the amount of interest you owe whilst providing you with available funds for any emergency that may arise.
In conclusion
Don’t give up. rising interest rates can be challenging. Talk to an expert lender if you need help understanding your options.
The expert lenders at The Hrkac Group are committed to helping borrowers get the most from their lending. Our in-house team of financial experts can help you create a financial plan that works for you and your individual circumstances, and can help you make the right decision about managing your home loan. If you want to discuss your options, speak to an expert Geelong Mortgage Broker at The Hrkac Group.
Our Geelong Mortgage Brokers’ expertise and experience in facilitating your home loan can help ensure a positive experience for you. To make an appointment to meet one of our friendly Geelong Mortgage Brokers today, feel free to contact us via email or phone (03) 5224 2366.
Liability limited by a scheme approved under Professional Standards Legislation.
At its July board meeting, the Reserve Bank of Australia (RBA) lifted the cash rate target by 50 basis points, in line with market expectations, bringing the official cash rate target to 1.35%. It also increased the interest rate on Exchange Settlement balances by 50 basis points to 1.25%.
This marks the third month in a row that the RBA has raised rates, with further increases expected over the course of this year as the central bank seeks to contain rising inflation. The third back-to-back rise follows an increase of 50 basis points in June – the largest increase since February 2002 – and 25 basis points in May. May’s increase was the first since 2010, as the central bank lifted the cash rate from its record low emergency level of 0.1%.
Global inflation is high
Global inflation is soaring. It is being boosted by COVID-19-related disruptions to supply chains, the war in Ukraine, and strong demand which is putting pressure on the capacity of production. Although monetary policy globally is responding to this higher inflation, it will be some time yet before inflation returns to target in most countries.
As part of the response, rate hikes are happening across the globe. The aim is to slow down economies and bring supply (production) and demand (spending) back into balance to address the soaring inflation rates. Nearly all central banks across the globe are lifting rates from ‘emergency’ levels to reflect more ‘usual’ functioning economies because of this.
In a statement from the RBA, Governor Philip Lowe had this to say on inflation in Australia:
“Inflation in Australia is also high, but not as high as it is in many other countries. Global factors account for much of the increase in inflation in Australia, but domestic factors are also playing a role. Strong demand, a tight labour market and capacity constraints in some sectors are contributing to the upward pressure on prices. The floods are also affecting some prices.
Inflation is forecast to peak later this year and then decline back towards the 2–3% range next year. As global supply-side problems continue to ease and commodity prices stabilise, even if at a high level, inflation is expected to moderate. Higher interest rates will also help establish a more sustainable balance between the demand for and the supply of goods and services. Medium-term inflation expectations remain well anchored and it is important that this remains the case. A full set of updated forecasts will be published next month following the release of the June quarter CPI.”
How COVID-19 and the war in Ukraine is driving inflation
An important factor to note in all of this is COVID-19. Workers are continuing to contract the virus and are forced to stay at home, resulting in fewer goods and services being produced. But economies are continuing to recover from the virus, with spending lifting. Unfortunately, spending is recovering more quickly than production. The other key factor is the war in Ukraine, driving up energy and food prices across the globe.
The Australian economy is resilient
In the statement from the RBA, Mr. Lowe commented on the Australian economy:
”The Australian economy remains resilient and the labour market is tighter than it has been for some time. The unemployment rate was steady at 3.9 % in May, the lowest rate in almost 50 years. Underemployment has also fallen significantly. Job vacancies and job ads are both at very high levels and a further decline in unemployment and underemployment is expected over the months ahead. The Bank’s business liaison program and business surveys continue to point to a lift in wages growth from the low rates of recent years as firms compete for staff in the tight labour market.
One source of ongoing uncertainty about the economic outlook is the behaviour of household spending. The recent spending data have been positive, although household budgets are under pressure from higher prices and higher interest rates. Housing prices have also declined in some markets over recent months after the large increases of recent years. The household saving rate remains higher than it was before the pandemic and many households have built up large financial buffers and are benefiting from stronger income growth. The Board will be paying close attention to these various influences on household spending as it assesses the appropriate setting of monetary policy.
The Board will also be paying close attention to the global outlook, which remains clouded by the war in Ukraine and its effect on the prices for energy and agricultural commodities. Real household incomes are under pressure in many economies and financial conditions are tightening, as central banks increase interest rates. There are also ongoing uncertainties related to COVID, especially in China.”
The Response
Central banks are ‘front loading’ rate hikes to try and get on top of inflationary pressures. That is, rates are being lifted more quickly and more aggressively than usual. The fear is that if higher rates of inflation take hold – become cemented in people’s consciousness – then it will take longer to bring the inflation rates back to preferred levels.
The risk with these ‘harder and faster’ rate increases is that they could cause economies to go into recession. Recessions are defined differently across the globe, but in Australia, the general definition of a recession is two consecutive quarters of economic contraction (declines in gross domestic product).
What this means for your mortgage
For a typical owner-occupier with a $500,000 mortgage and 25 years remaining, this increase will see their monthly repayments rise by $137, according to RateCity.
Their total increase to date from the May, June, and July rate hikes would be $333 per month.
For a borrower with a $1 million mortgage, today’s decision will add $273 to their monthly repayments, bringing their total increase to $665 per month since April.
CoreLogic figures also showed national house prices fell for the second consecutive month in June by 0.6 %.
In conclusion
From the statement from the RBA:
“Today’s increase in interest rates is a further step in the withdrawal of the extraordinary monetary support that was put in place to help insure the Australian economy against the worst possible effects of the pandemic. The resilience of the economy and the higher inflation mean that this extraordinary support is no longer needed. The Board expects to take further steps in the process of normalising monetary conditions in Australia over the months ahead. The size and timing of future interest rate increases will be guided by the incoming data and the Board’s assessment of the outlook for inflation and the labour market. The Board is committed to doing what is necessary to ensure that inflation in Australia returns to target over time.”
If you would like a free home loan review from our HG Mortgage broker team, download the below document and return it to us or email mortgages@hrkacgroup.com.au.
